


< !--cell-- >
< !--end grid-x-->


A Bridge Too Far?
In a novel move, a new transportation-funding law is sending billions from the Fed's surplus account to help pay for roads, bridges, and mass transit
Econ Focus
Third Quarter 2015
For drivers across the United States who fret over growing congestion and aging roads and bridges, some welcome news arrived when President Obama signed a sweeping five-year transportation bill into law in December. The $305 billion measure boosted funding across the board, including an $8 billion increase for highways over current levels, along with an additional $2 billion for mass transit, just to name two examples.
The unusual twist is that roughly $36 billion of the law's funding comes from the Federal Reserve. When lawmakers couldn't agree on how to boost financing via traditional means — including raising the gas tax — they found their source within the Fed instead. Although senior Fed officials objected that using a central bank to fund specific fiscal needs would set a worrisome precedent, the strong political momentum to complete the long-stalled bill persuaded large majorities in both parties to throw their support behind the underlying legislation.
The transportation legislation taps into two Fed sources: $19.3 billion as an immediate transfer from the Fed's capital surplus account — a pool of funds the Fed has routinely set aside since its early years — followed by another $14 billion over the next five years; and a further $2.8 billion diverted from the Fed's dividend payments to member banks, also over five years. Although it isn't the first time Congress ordered Fed surplus-account funds to be channeled to the Treasury, this case represents the largest such transfer ever, both in nominal and in percentage terms.
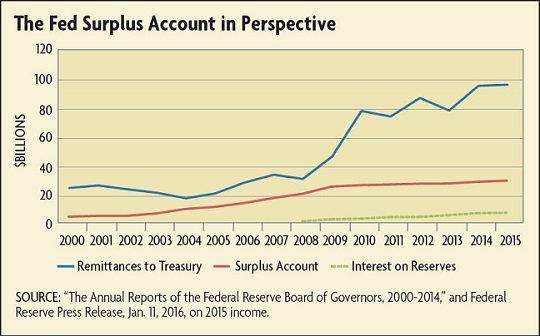
Previous transfers from the Fed's surplus account were relatively small and rare, and they generally went toward general deficit reduction. In this case, however, Congress ordered the money to be channeled to the Treasury for a specific fiscal need unrelated to monetary policy: surface transportation. It also required that the surplus account, which was $29.3 billion at the end of December 2015, be capped at $10 billion — the first permanent limit ever imposed — and that any surplus funds in excess of that cap go back to the Treasury. The cut in dividend payments was also a first. Altogether, these provisions allowed lawmakers to close a financing gap in the legislation that had grown over the years due to broad political reluctance to hike the long-frozen gas tax, the primary source of revenue for highway funding. Without the Fed money, financing the measure would have been a far heavier lift, according to lawmakers.
"There is plenty of profit sloshing around there that would come back to the Treasury anyway," was how Sen. Dan Coats (R-Ind.) described the prevailing sentiment to Roll Call. Most lawmakers viewed the surplus account as "easy money," he added.
This may have indeed seemed like easy money to some, but the move prompted concerns from economists and Fed policymakers about the underlying principle of central bank independence. They also noted that the funding fix didn't represent a long-term budget solution on the fiscal side.
Fed's Rainy Day Fund or Congress' Piggy Bank?
There is often confusion between the Fed's "surplus account" and the Fed's (far larger) "operating surplus," which is income left over after expenses and sent to the Treasury on a weekly basis. There is also a common perception that the surplus account has been traditionally used as a "rainy day fund" in Fed operations, even though that isn't exactly the case, either. The Fed doesn't need such a surplus the way a bank needs capital as a buffer, because it has the power to expand or contract the amount of money in the economy. And while many other central banks have similar accounts, not all do. Nor has the surplus account played a major role when the Fed has responded to emergencies, such as its various forms of lending during the 2007-2009 financial crisis.
Instead, a more accurate description of the surplus account is that it's one piece of a larger package that dates back to the Fed's beginnings, namely, the framework that set up the relationship between the Fed and member banks. This is because the surplus account — until the highway legislation — was tied directly to another component of the Fed-bank relationship: It had to equal the amount of stock that member banks hold in the regional Reserve Banks as paid-in capital. After several revisions in the Fed's early decades, the Federal Reserve Board of Governors set this ratio in 1964 so there wouldn't be ambiguity about the surplus account's required size. Due to this peg, the surplus account grew along with the paid-in capital account as more banks joined the System and as their assets grew over the years. In 2001, for example, the surplus account totaled $7.3 billion; by 2015, it had expanded to $29 billion (see chart below).
Readings
Carpenter, Seth, et al. "The Federal Reserve's Balance Sheet and Earnings: A Primer and Projections. " International Journal of Central Banking, March 2015, vol. 11, no. 2, pp. 237-283.
Goodfriend, Marvin. "Monetary Policy as a Carry Trade." Monetary and Economic Studies, Bank of Japan, November 2014, pp. 29-44.
Goodfriend, Marvin. "The Relevance of Federal Reserve Surplus Capital for Current Policy." Economic Policies for the 21st Century, March 17, 2014.
"Federal Reserve System: The Surplus Account." General Accounting Office, September 2002.
Christensen, Jens, Jose Lopez, and Glenn Rudebusch. "A Probability-Based Stress Test of Federal Reserve Assets and Income." Federal Reserve Bank of San Francisco Working Paper No. 2013-38, December 2013.
 Download article
Subscribe to Econ Focus
Receive an email notification when Econ Focus is posted online.
By submitting this form you agree to the Bank's Terms & Conditions and Privacy Notice.
Contact Us