


< !--cell-- >
< !--end grid-x-->



Unpacking the Meat Industry
Changes in the meat supply chain have brought benefits, but are vulnerabilities a cause for concern?
Econ Focus
Fourth Quarter 2020
COURTESY OF PERDUE FARMS
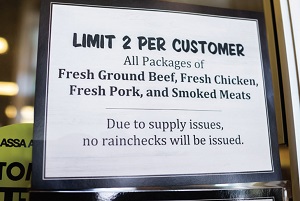
The COVID-19 pandemic hit meat processing facilities in the United States suddenly and dramatically. Between April 9 and April 27, more than 4,900 COVID-19 cases were reported among 115 different meat and poultry processing facilities. Rising cases and contamination fears led major processors, such as Smithfield, Va.-based Smithfield Foods, to shut down plants in April. During this period, large retailers like Kroger and Costco implemented meat rationing. These developments prompted President Donald Trump to invoke the Defense Production Act on April 28, compelling plants to remain open — and brought the resilience of the meat supply chain under scrutiny.
Our Related Research
"The State of Agriculture in the Fifth District and Beyond." Investing in Rural America Conference, Oct. 7, 2020
Waves of Changes
Beginning in the 1970s, consumer spending on food as a share of total disposable income declined, yet consumer demand shifted toward products that were consistent, ready-made, and healthier, driving the evolution of the meat supply chain. Whereas Americans in 1960 spent an average of 17 percent of their disposable personal income on food, USDA data reveal that by 2019, Americans spent an average of only 9.5 percent of their income on food. Their data suggest the decline has been driven most by decreased spending on food at home — that is, on groceries.
In addition, starting in the 1970s, higher labor participation among women further shifted consumer preferences toward ready-made products, one-stop shopping, and eating away from home. Higher patterns of meat consumption and dining out also increased the demand for meat products over this period. Moreover, consumer demand for selection variety and supply consistency at low cost prompted consolidation and new procurement practices among the meat processing, retail, and upstream segments of the supply chain.
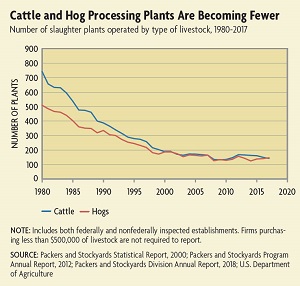
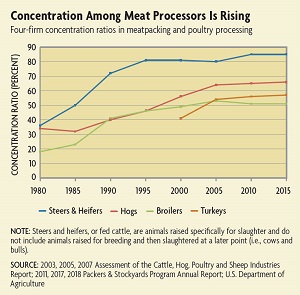
Meat processors and packagers were the first segment of the meat supply chain to undergo a significant wave of consolidation, from 1972-1992. Consolidation in the poultry industry in the 1960s reduced the price of chicken while increasing output and product selection. This caused poultry consumption to surge while beef and pork processors' profits fell. Alan Barkema, Mark Drabenstott, and Nancy Novack, then with the Kansas City Fed, explained in a 2001 article that the reduced profits prompted cost-cutting efforts and renewed competition. Meat processors realized cost savings from improved technology for storing and cutting animals and reorganizing the production line with more low-wage workers, allowing for efficiency improvements. For example, larger plants adopted technology to support more fabrication — that is, cutting — of carcasses into wholesale cuts, reinforcing their cost advantages of scale. Subsequently, these processors' transportation costs also declined since they were shipping boxes of products rather than carcasses, while they shifted toward specialization in a single species in order to increase the efficiency of their technological investments. For example, Smithfield Foods, founded in 1936, was on the verge of bankruptcy in the early 1970s before it transformed by streamlining its operations, acquiring underperforming pork companies, and slashing overhead by reducing middle-tier workers, leading to strong growth throughout the late 1970s and 1980s.
A 2005 USDA report found meatpacking and processing workers' average wages dropped about a third, while meatpacking plant size doubled and output per meatpacking worker increased 45 percent from 1972-1992. "Both the introduction of scale economies from technology and the reduction in union wages among workers in large plants in the 1980s meant that larger plants now had a significant cost advantage over smaller plants," says James MacDonald of the University of Maryland, formerly acting chief of the Structure, Technology, and Productivity branch at the USDA's Economic Research Service.
Sidebar
A second key aspect of regional food systems is their community focus, which can be increased through local intermediaries such as food hubs. (See sidebar.) Consumers value these community ties — the NGA found 57 percent of shoppers support their local supermarket because it is linked to the community.
Additionally, other groups, such as meat trade organizations, may work to improve ties between farmers and producers in their area. "We have a lot of programs; we're engaged heavily in education and providing resources for farmers from soil health to animal well-being, maximizing feed efficiency to managing manure as a resource," said Andy Curliss, who was then CEO of the North Carolina Pork Council, in a July interview. "We're a forum where our farmers can learn about and discuss new and innovative things."
One proposal aimed at increasing local meat consumption ties is the Processing Revival and Intrastate Meat Exemption (PRIME) Act, a bill before the House Agriculture Committee with bipartisan co-sponsors. Current federal law requires meat products to be inspected at USDA- or state-monitored plants that meet federal guidelines before public sale. The PRIME Act would allow meat processed at custom plants complying with state laws to be sold directly to consumers and establishments in the same state and would exempt that meat from federal inspection requirements. Expanding possible processors could allow small farmers to use state-regulated custom plants to reduce costs. Proponents say this would decrease the price of local meat, help small processors, and allow businesses to source local meat more affordably while reducing chokepoints in the supply chain. Several meat trade associations, such as the National Pork Producers Council, oppose the bill, contending that the commercial sale of nonfederally inspected meat products could compromise food safety.
Consumers' Choice
One critical question is whether consumers will actively seek more resilient meat supplies — and pay for them. In the case of regional food systems, local foods are generally more expensive, and consumers may be unwilling or unable to pay premiums for local or higher quality meat. "In general, consumers who pay premiums for local or socially responsible products are more affluent," Gomez notes. "Income disparities may prevent some households from paying those price premiums. "Furthermore, the NGA's 2018 survey report found a potential price increase of 10 percent caused 58 percent of consumers to switch supermarkets.
Overall, a transition toward greater resilience likely requires more research into consumer preferences and the trade-off between efficiency, consistency, safety, and prices. "It will be gradual, and we still need to do a lot of thinking about that," says Gomez. "There must be incentives for companies to decentralize. We need more research to identify the right food supply chain infrastructure required to support a decentralized food system, and we need a better understanding of consumer preferences for regionally and locally produced foods." As long as consumers and voters view the probability of additional significant disruptions like the COVID-19 pandemic as low, the perceived benefits of modern supply chains' cheap and consistent products may outweigh the value of more resilience.
Readings
Barkema, Alan, Mark Drabenstott, and Nancy Novack. "The New U.S. Meat Industry." Federal Reserve Bank of Kansas City Economic Review, Second Quarter 2001, pp. 33-56.
Carpenter, Surekha. "Food Hubs: Mission-Driven Local Food Systems in the Fifth District." Federal Reserve Bank of Richmond Community Scope, 2019, vol. 7, no. 2, pp. 1-11.
MacDonald, James M., and William D. McBride. "The Transformation of U.S. Livestock Agriculture: Scale, Efficiency, and Risks." U.S. Department of Agriculture Economic Research Service, Economic Information Bulletin No. 43, January 2009.
Sexton, Richard J., and Tian Xia. "Increasing Concentration in the Agricultural Supply Chain: Implications for Market Power and Sector Performance." Annual Review of Resource Economics, October 2018, vol. 10, pp. 229-251. (Article available with subscription.)
 Download article
Subscribe to Econ Focus
Receive an email notification when Econ Focus is posted online.
By submitting this form you agree to the Bank's Terms & Conditions and Privacy Notice.
Contact Us