


< !--cell-- >
< !--end grid-x-->



Corporate Crypto Crowdfunding
The technology behind cryptocurrencies shows promise for raising capital but has also drawn scrutiny from regulators
Econ Focus
First Quarter 2019
Transferring computer files used to require loading them onto a flash drive, burning them to a CD, or (if you are old enough to remember) writing them to a floppy disk. Today, everything is in the cloud. Services like Dropbox, Google Drive, and Apple's iCloud allow users to upload files to remote computer servers and retrieve them later from any device. Cloud storage systems tend to be owned by large corporations. But American computer scientist Juan Benet thought he had a better idea: What if, instead of relying on companies to build and maintain servers for cloud storage, it was possible to share excess storage capacity on personal computers?
That's what Protocol Labs, the company Benet founded, set out to do in 2014. Drawing inspiration from Bitcoin, the decentralized payment system that had launched in 2009, Protocol Labs' Filecoin would be a new digital currency used exclusively on a decentralized cloud storage network. Users could earn filecoins by offering storage on their computers for use on the network. What's more, the sale of filecoins could fund the creation of the network itself.
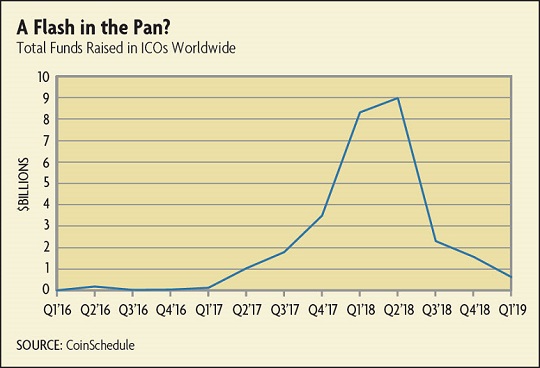
Protocol Labs' $257 million sale of filecoins was an example of what has come to be known as an initial coin offering, or ICO. In an ICO, entrepreneurs sell bitcoin-like digital tokens to raise capital for their businesses, similar to how companies have traditionally raised money by selling stock in an initial public offering (IPO). Like stocks, tokens are typically tradeable, but unlike stocks, they usually don't confer any ownership of the issuing company. Instead, they are often redeemable in the future for some good or service developed by the issuer. In 2017 and 2018, ICOs raised more than $27 billion worldwide — nearly half as much as traditional IPOs in the second quarter of 2018 alone.
ICOs have attracted the attention of more than just digital startups like Protocol Labs. The venerable Eastman Kodak Company got in on the action by selling KODAKCoins that could be used to purchase rights to digital photographs on an online platform. Early proponents saw ICOs as a way to both enable new decentralized platforms and cheaply raise funding by avoiding traditional corporate finance channels and going directly to the customers.
"The idea was that ICOs would be transparent, secure, and self-regulating, operating outside of national borders and regulatory frameworks," says Nick Morgan, a partner with the law firm Paul Hastings who focuses on securities regulation. "That turned out to be incorrect."
Through a series of actions starting in mid-2017, the U.S. Securities and Exchange Commission (SEC) made it clear that most tokens sold in ICOs met the definition of a security and were therefore subject to the same requirements as traditional stock offerings. Perhaps because of this increased attention from regulators, ICO activity has slowed dramatically of late, inviting speculation that the ICO boom had mostly been about evading regulatory scrutiny. In the first quarter of 2019, ICOs raised about $600 million compared with more than $8 billion over the same period the year before. Nevertheless, ICOs' rapid rise captured the attention of economists who are exploring whether the technology behind cryptocurrencies might improve how corporations raise money.
Funding Phenomenon
Cryptocurrencies such as Bitcoin proved that it was possible to assign and track ownership of digital objects without a central authority. The technology that enabled this was actually a variant on an old idea: the simple ledger. Bitcoin's ledger, known as the blockchain, contains a record of every transaction ever made using the cryptocurrency. The blockchain's new twist on the ledger was to distribute a copy to all Bitcoin users, making all transactions public knowledge and also making it impossible for any one user to alter the ledger and fake a transaction without the consent of a majority of the network. This allowed Bitcoin to serve as a decentralized payment method that was virtually impervious to fraud.
At first, the blockchain was simply a tool for Bitcoin transactions. But users soon began to explore other functions, such as embedding contracts into the blockchain. These "smart contracts" are similar to computer programs: They specify actions that occur automatically when certain conditions are met. In 2012, a software engineer and Bitcoin enthusiast named J.R. Willett suggested that such contracts could be used to raise funding for new projects or even entire companies. In a white paper, he explained how someone could write a smart contract that laid out a business proposal and allowed anyone to purchase a stake in that business in exchange for bitcoins. Those bitcoins would provide the funding to create the new venture, fulfilling the same role as traditional venture capital.
No one jumped on Willett's idea immediately, so he took it upon himself to launch Mastercoin in 2013 as a proof of concept. He raised half a million dollars in bitcoin, and the first ICO was born. It took a few more years for ICOs to catch on, but by 2017, the market took off. (See chart below.) Some advocates speculated that it might replace traditional corporate funding entirely, but economists have generally been more skeptical of its prospects.
 Download article
Subscribe to Econ Focus
Receive an email notification when Econ Focus is posted online.
By submitting this form you agree to the Bank's Terms & Conditions and Privacy Notice.
Contact Us