


< !--cell-- >
< !--end grid-x-->


Learning About the Labor Market from High-Frequency Data
Employment in the United States experienced the sharpest decline on record in April as the negative economic effects of the COVID-19 pandemic and social distancing measures caused employers to cut almost 21 million jobs, on net. (The next largest single-month decline was almost three-quarters of a century earlier, in September 1945, when almost 2 million jobs were lost.) Yet the full severity of the job loss was not known for quite a while: More than seven weeks passed from when the first state, California, issued a stay-at-home order on March 19 to when the Bureau of Labor Statistics (BLS) released the first national employment report fully reflecting the onset of the crisis, the report for April released on May 8.
Traditional sources of employment data are lagged, sometimes by a lot. At the national level, the employment report for a given month is typically released on the first Friday of the following month. And those data are based on a survey of firms that takes place around the middle of the month. This is why the jobs report for March had yet to show the full effect of the widespread social distancing measures, since many of those were put into place in late March and early April.
The BLS releases employment data for state and lower levels of geography at even greater lags. For example, the state-level data are typically lagged by another two weeks, coming out in the middle to the end of the month. County and metro employment and unemployment data are released a few weeks after that. And the most comprehensive source of data on local employment comes from the Quarterly Census of Employment and Wages, which is released between five and six months after the quarterly period ends. (For more on state and local labor market data, see "State Labor Markets: What Can Data Tell (or Not Tell) Us?" Econ Focus, First Quarter 2015.)
These lags are not new, or unknown, but in times of rapidly changing circumstances, the data are not sufficiently able to keep up with economic conditions. Knowing that the official employment counts would not be available for some time, economists, policymakers, and analysts looked during the COVID-19 crisis to other sources that could shed light on how the virus and the shutdown of economic activity were affecting the labor market. This includes the Federal Open Market Committee (FOMC), which, according to the minutes from meetings held in March, April, and June, found that traditional economic data could not capture the rapidly evolving situation; instead, the committee referenced high-frequency data.
Unemployment Insurance Claims
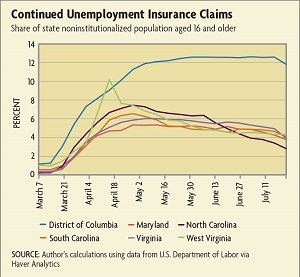
One source that directly shows changes in labor markets on an early basis, which the FOMC relied on in March, April, and June, is weekly unemployment insurance claims. Unemployment insurance programs are administered by individual states. Every state is required to report the number of initial and continued claims to the Department of Labor, which in turn releases that data to the public on the Thursday of the following week. As their names imply, initial claims are the number of new claims filed in the reference week, and continued claims are the number of workers who were already collecting unemployment benefits and remained unemployed in the reference week.
Because these data are timelier than payroll employment data from the BLS, they can serve as an early indicator of an economic downturn. In normal times, there is some variation in these data week to week as people move from employment to unemployment and back to employment or as some people decide to leave the labor force rather than continue to look for a new job. There are also seasonal patterns in the data, but those can be removed by applying a statistical procedure known as seasonal adjustment. Hindsight shows that in the weeks leading up to the starts of the last several recessions, the claims data tended to rise steadily and sometimes rapidly.
Take the Great Recession, for example. Data from the payroll survey began showing the decline in employment in February 2008, which was the first of 21 consecutive months of job losses. If we look at the six months prior to that, from August 2007 through January 2008, the payroll data were not alarming, with a slight increase in total employment in the United States (0.3 percent or 388,000 jobs). At the same time, though, initial claims (after being adjusted for seasonal trends) began to steadily increase, and seasonally adjusted continued claims rose 12.4 percent or by 314,000 jobs.
Likewise, evidence of an effect on employment from the COVID-19 pandemic appeared in the initial and continued claims data several weeks before the payroll data were available — but this time at rates never seen before. The first increase in initial claims in the United States came in the week ending March 14, when the number of claims rose 33.3 percent or by around 70,000. In the next week, initial claims rose more than tenfold from around 280,000 claims to almost 3.3 million and then more than doubled the week after to almost 6.9 million. The same data for Fifth District jurisdictions show similar trends except for West Virginia, where the initial claims data didn’t peak for another couple of weeks.
Our Related Research
Richmond Fed Surveys of Business Activity
"Interpreting Unemployment Data in the Time of COVID-19," Regional Matters, Aug. 7, 2020
Emerging Sources
A few newer sources have become available. The first is the Real-Time Population Survey (RPS), which is a joint effort between academic economists and the Dallas Fed. The goal of the RPS is to provide a survey similar to the BLS' household survey of employment and unemployment (the Current Population Survey), but it differs in that the RPS is conducted online twice a month, and the results are made available with a shorter lag. The results of the RPS are plotted with the official BLS survey measures of employment and unemployment in reports available on the Dallas Fed's website.
The U.S. Census Bureau also began conducting two new high-frequency surveys to better understand the effects of COVID-19 on the economy. The first was the Household Pulse Survey, which was a weekly survey that began on April 23 and concluded on July 21. The results of the survey were posted one week after the survey period closed and gave insights into issues such as childhood education (including availability of computers and internet), employment, household spending and food sufficiency and insufficiency, health, and housing. The data, which are available at a national, state, and metropolitan level (for the 15 largest metro areas), are still available on the U.S. Census Bureau's website at the time of writing this article.
The second new survey from the U.S. Census Bureau is the Small Business Pulse Survey, which began on May 14 and is still ongoing. It is designed to provide information on small-business operations and finances, including any government support they have received and their outlook for the near future. These data are available at the national and state levels and for the 50 most populous metro areas. An interactive dashboard shows which industries and areas of the country have a relatively higher share of small businesses being negatively or positively affected by the pandemic and where firms are the most optimistic or pessimistic about the near future.
Conclusion
Although none are without limitations, each of these high-frequency data sources offers a glimpse into the labor market in nearer to real-time. The initial unemployment insurance claims data were particularly useful in understanding how many and, in some cases, the characteristics of workers who were being hurt during the crisis when many businesses were scaling back or shutting down operations.
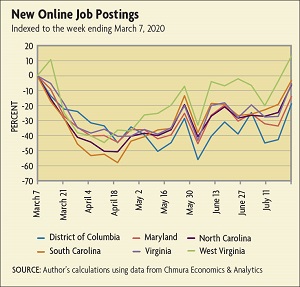
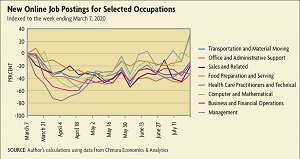
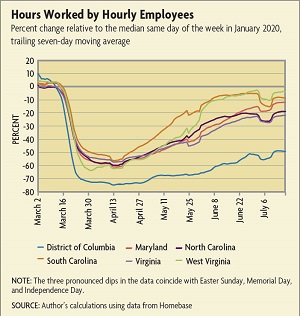
The continued claims data were (and will continue to be) a useful indicator to track the number of people who are collecting unemployment each week. In terms of labor demand, online job posting data offer a glimpse into the types of jobs that employers are recruiting for, and the Homebase data show trends in the hours worked by hourly employees in some of the hardest-hit industries. Lastly, the Richmond Fed has used and will continue to use the ability to add special, topical questions to its surveys of business conditions to understand the effects of the pandemic.
The Richmond Fed has created Pandemic Pulse, an area on its website that features interactive charts of various high-frequency indicators.
 Download article
Subscribe to Econ Focus
Receive an email notification when Econ Focus is posted online.
By submitting this form you agree to the Bank's Terms & Conditions and Privacy Notice.
Contact Us